Cover photo: Suzuki Auto South Africa, from the shoot on its own Jimny 5-door finance offer page.
Most people buying a Jimny on finance ask the same thing first. What will it cost me a month?
The Reserve Bank put prime up to 10.75% from 25 September 2026. At that rate, with 10% down over six years and no balloon, a new Jimny costs about R7,600 to R8,400 a month. A used current Jimny costs about R5,000 to R6,400. An older 1.3 costs about R2,600 to R3,800.
That is before insurance. It is also well above the “from R5,799 a month” you see in the adverts. This guide shows why, and what the deposit, the term and a balloon do to the number.
The short answer
- Most money saved: the biggest deposit you can manage, the shortest term you can carry, and no balloon.
- New Jimny under about R7,000 a month: buy a discounted new car, put down 20% or more, or take a balloon and plan to trade in.
- Budget around R5,000 to R5,500: a used 3-door from 2019 to 2022, 10% down, no balloon.
- Budget under R4,000: an older 1.3, and ask the bank early whether it will finance a car that old.
What a Jimny costs a month
These are typical asking prices on live Jimny adverts we analysed on 23 September 2026. The new prices are Suzuki’s list prices. Every monthly figure uses 10% down, 72 months and no balloon. It includes the bank’s fees, but not insurance.
| Jimny | Adverts | Typical asking price | A month at prime (10.75%) | A month at prime plus 2 (12.75%) |
|---|---|---|---|---|
| Older 1.3, 2008 to 2012 | 46 | R147,000 | R2,593 | R2,731 |
| Older 1.3, 2016 to 2018 | 83 | R216,000 | R3,767 | R3,970 |
| Used 3-door, 2019 | 29 | R286,000 | R4,958 | R5,226 |
| Used 3-door, 2022 | 185 | R320,000 | R5,537 | R5,836 |
| Used 5-door, 2024 | 249 | R370,000 | R6,388 | R6,734 |
| New 5-door GL manual, advertised | 52 | R404,900 | R6,981 | R7,360 |
| New 5-door GL manual, list price | R439,900 | R7,577 | R7,988 | |
| New 3-door GLX manual, list price | R444,900 | R7,662 | R8,078 | |
| New 5-door GLX auto, list price | R489,900 | R8,428 | R8,886 |
Your own rate may be higher than prime, so we show prime plus 2 as well. Nobody publishes an average rate. Treat both columns as a guide, not a promise.
The market has three price steps, and each is a very different loan. An older 1.3 asks about R190,000 (193 adverts). A used current Jimny asks about R349,000 (929 adverts). A new or nearly new one asks about R440,000 (647 adverts). Our Jimny price guide and price by year guide break the prices down further.
Suzuki’s new prices
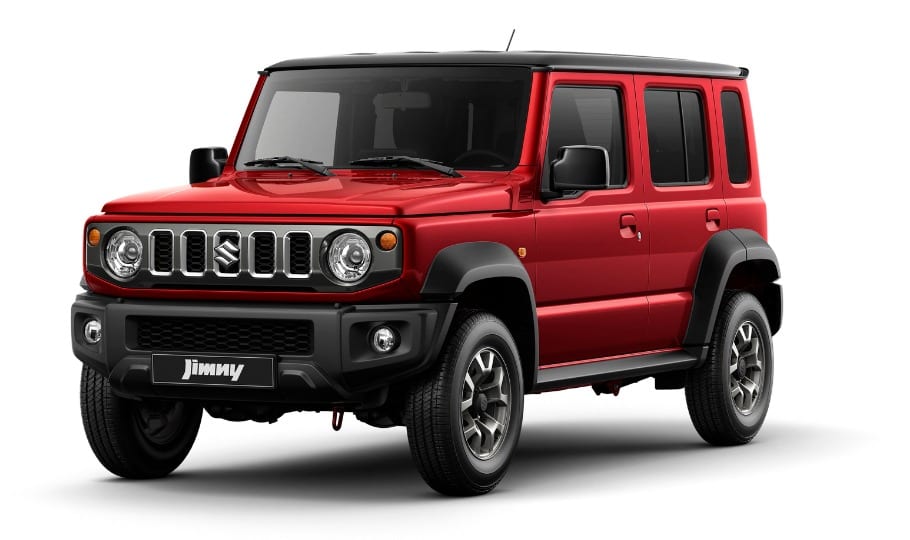
| New Jimny | List price |
|---|---|
| 5-door GL manual | R439,900 |
| 3-door GLX manual | R444,900 |
| 3-door GLX manual with auto braking pack | R459,900 |
| 3-door GLX auto | R466,900 |
| 5-door GLX manual | R467,900 |
| 3-door GLX auto with auto braking pack | R481,900 |
| 5-door GLX auto | R489,900 |
Prices from Suzuki Auto South Africa’s own pages, seen on 23 September 2026. Not sure which body suits you? Our 3-door vs 5-door guide covers it.
The rate: prime is 10.75%
Car loans in South Africa are priced against prime. On 23 September 2026 the Reserve Bank raised its rate, taking prime to 10.75% from 25 September. That was the second hike of 2026, after one in May.
Your bank sets your own rate, from your credit record and your deposit. Ask for it in writing.
Most car loans are linked to prime. So your instalment is not fixed. When prime goes up, your payment goes up too, for all six years. September’s hike alone added about R50 a month to a new 3-door GLX. If you want certainty, ask your bank whether it offers a fixed rate.
One day your bank may quote “repo plus” instead of “prime plus”. It is the same number said a different way.
What “from R5,799 a month” really means
Suzuki’s own advert for the 5-door GL says “from R5,799 p/m”. The fine print, seen on 23 September 2026, tells you what sits behind it.
| What the advert assumes | Figure |
|---|---|
| Car | 5-door GL manual, R439,900 |
| Deposit | 10% |
| Term | 72 months |
| Interest rate | 9.59% |
| Balloon still owed at the end | 35%, R153,965 |
| Once-off initiation fee | R1,207.50 |
| Monthly service fee (in the instalment) | R69 |
| Insurance | Not included |
The finance is Suzuki Mobility Finance, a product of WesBank. The instalment can go up with your credit record. The advert was also priced when prime was 10.50%, before the September hike.
Take the balloon away, keep everything else the same, and the car costs about R7,300 a month. So the low number is mostly the balloon. You still owe about R154,000 at the end of year six. And you pay about R39,000 more over the life of the loan than you would without the balloon.
Suzuki’s 3-door advert says “from R5,999 a month”. We could not find the terms behind that one. Ask the dealer what deposit and balloon it assumes.
Deposit, term and balloon
Three things set your instalment: how much you put down, how long you pay, and whether you leave a lump sum for the end. The tables below all use the same car, a new 3-door GLX manual at R444,900, at prime.
The deposit
| Deposit | A month (72 months, no balloon) | Cost above the car’s price |
|---|---|---|
| None | R8,503 | R167,333 |
| 10% (R44,490) | R7,662 | R151,261 |
| 20% (R88,980) | R6,821 | R135,189 |
| 30% (R133,470) | R5,980 | R119,116 |
Every extra R10,000 you put down cuts the instalment by about R190 a month. A trade-in counts as deposit. Check what your current car is worth first. A dealer will offer you less than the price on an advert, so do not plan on the full amount.
The term
| Term | A month (10% down, no balloon) | Total you pay | Cost above the car’s price |
|---|---|---|---|
| 48 months | R10,400 | R543,705 | R98,805 |
| 60 months | R8,751 | R569,559 | R124,659 |
| 72 months | R7,662 | R596,161 | R151,261 |
| 84 months | R6,893 | R623,501 | R178,601 |
“Total you pay” includes the deposit and the bank’s fees. Five years instead of six costs about R1,090 more a month. But it saves about R26,600 in the end. Pick the shortest term you could still carry if your income dips.
The balloon
A balloon is a lump sum you still owe at the end of the loan. Dealers and banks also call it a residual. It lowers your instalment because you do not pay it off month by month. But you pay interest on it the whole time.
| Balloon | A month (10% down, 72 months) | Lump sum due at the end | Total you pay | Cost above the car’s price |
|---|---|---|---|---|
| None | R7,662 | R0 | R596,161 | R151,261 |
| 20% | R6,777 | R88,980 | R621,409 | R176,509 |
| 30% | R6,334 | R133,470 | R634,032 | R189,132 |
| 35% | R6,113 | R155,715 | R640,344 | R195,444 |
A 30% balloon saves about R1,330 a month. It costs about R38,000 more over six years. And you must find R133,470 at the end.
Balloons are now normal in South Africa. WesBank told EWN in June 2026 that about 30% of its car loans include one. It said the typical balloon has grown to about a third of the amount financed.
Is a balloon safe on a Jimny?
Ask on 4x4community and most replies call a big balloon a rental, or a trap. Others say it lets you drive a car you could not afford otherwise. The real test is simpler. Will the car be worth more than the balloon when it falls due?
On past form, the Jimny passes that test well. When the current Jimny launched in 2018, a 3-door GLX manual cost R299,900. A 2019 3-door still asks about R286,000 (29 adverts). A 30% balloon on that car would have been about R90,000. Our resale value guide has the full story.
But the past is not a promise, for three reasons.
- Old Jimnys ask so much partly because new prices have risen by almost half since 2018. A Jimny bought at today’s prices may not get that lift.
- Prices are softening now. Three in four price changes on Jimny adverts in the last three months were cuts (1,701 of 2,226). The typical cut was about R9,000.
- The waiting lists are long gone. Hundreds of new Jimnys are advertised, and new stock typically sits for about three months.
The bigger risk is wanting out early. Here is what you would still owe on a new 3-door GLX (R444,900) at prime.
| Deal | Owed after 1 year | Owed after 2 years | Owed after 3 years |
|---|---|---|---|
| 10% down, 72 months, no balloon | R351,000 | R295,000 | R233,000 |
| 10% down, 72 months, 30% balloon | R368,000 | R331,000 | R289,000 |
| No deposit, 84 months, 35% balloon | R417,000 | R384,000 | R348,000 |
A two-year-old Jimny, a 2024, asks about R370,000 on live adverts. So with no deposit and a big balloon, you owe more than the car’s advert price after two years. A dealer’s trade-in offer will be lower still. You would have to pay cash just to get out.
With 10% down and no balloon, you owe well under what the car is worth. If you might sell early, put money down.
When a balloon falls due, you have three choices. Pay it in cash. Borrow it again, with more interest on an older car. Or sell the car and settle it. If the car is worth less than the balloon, selling will not clear it.
A balloon suits you if you will trade in when the loan ends, have put money down, and accept paying more in total. It does not suit you if you plan to keep the Jimny for ten years.
Where to get the loan
The Suzuki dealer. Suzuki’s own finance is Suzuki Mobility Finance, a product of WesBank. You can apply for pre-approval online before you visit. Suzuki says the rate depends on your credit record.
Your own bank. Get a quote from your bank before you shop. Then walk in with a number and ask the dealer to beat it.
Ask for a deal first. New Jimnys often advertise well under Suzuki’s list price. That shrinks the loan before you talk about rates.
| New Jimny | List price | Adverts | Typical asking price | A month at list | A month at the asking price |
|---|---|---|---|---|---|
| 5-door GL manual | R439,900 | 52 | R404,900 | R7,577 | R6,981 |
| 5-door GLX manual | R467,900 | 83 | R434,900 | R8,053 | R7,492 |
| 5-door GLX auto | R489,900 | 169 | R459,900 | R8,428 | R7,917 |
Same terms as before: 10% down, 72 months, prime, no balloon. R30,000 off the price is about R500 a month off the instalment. Some advertised prices may leave out on-the-road fees, so ask for the full price in writing.
New or used on finance
A new Jimny currently comes with Suzuki’s five-year or 200,000 km warranty and a four-year or 60,000 km service plan. For a financed car that matters. No big repair bill lands on top of the instalment for years.
A used Jimny means a smaller loan. A typical 2022 3-door costs about R2,100 a month less than a new 3-door GLX. A 2024 5-door with about 34,000 km asks about R70,000 less than a new GL. That is about R1,190 a month less. It may still have some of Suzuki’s warranty left. Ask the dealer what remains.
Ask each bank for its rate on the exact car you want, new or used. Rates and rules differ by bank. Many banks also limit how old a car they will finance, which matters for an older 1.3. Ask early.
A few used-car rules worth knowing:
- Dealer or private seller. Buy from a dealer and the Consumer Protection Act gives you six months to claim a repair, a swap or a refund for a serious fault. Normal wear for the car’s age does not count. A private sale gives you no such right.
- The seller still owes the bank. Then the bank owns the car. Pay the bank, not the seller, and get the papers released.
- Too cheap to be true. Scammers advertise fake “bank repossessed” cars at low prices and ask for a deposit to “pull” them from auction. WesBank told EWN it never sells an auction car outside the auction. A current Jimny for under about R230,000 is a write-off, a mistake or a scam. Never pay a deposit on a car you have not seen.
- Parts already fitted. Many used Jimnys come with bigger tyres, a lift or a rack. Find out what was added and tell your insurer.
What your monthly budget buys
The same terms again: 10% down, 72 months, no balloon. The last column counts live adverts on 23 September 2026.
| A month | Finances a car up to (prime) | Up to (prime plus 2) | What that buys on live adverts |
|---|---|---|---|
| R3,000 | R171,000 | R162,000 | An older 1.3, mostly 2008 to 2015 (70 of 193) |
| R4,000 | R230,000 | R218,000 | Almost any older 1.3 (165 of 193) |
| R5,000 | R288,000 | R273,000 | The cheapest current Jimnys, mostly high-km 3-doors (69 of 929 used) |
| R6,000 | R347,000 | R329,000 | Half of all used current Jimnys, mostly 3-doors (461 of 929) |
| R7,000 | R406,000 | R385,000 | Nearly any used Jimny (867 of 929), and some discounted new ones |
| R8,000 | R465,000 | R441,000 | Most new Jimnys (520 of 647 new and nearly new) |
A balloon on an older 1.3 is a poor idea. You would owe a large lump sum on a car that could be 20 years old by then. Browse current Jimnys for sale with your budget in mind.
The rest of the bill
Insurance is not optional. The law lets the bank make you insure the car for as long as you owe money on it. Get two or three quotes before you sign. Premiums depend on you, your area and the car, so we do not quote one here.
Declare every accessory. Jimny owners fit racks, tyres and lifts. Tell your insurer about each one and keep the invoices, or it may not be covered. Our accessories guide and lift kit guide cover what owners fit and what it costs.
The gap. If the car is stolen or written off, the insurer pays what the car is worth. That can be less than you owe the bank, most of all with a small deposit and a big balloon. “Shortfall” or “top-up” cover is sold to fill that gap. The insurance ombud has warned that some of these policies leave out the balloon, the interest or accessories like roof racks. Read what it excludes before you buy it.
Credit life. The bank may ask you to take out credit life cover, which pays the loan if you die or cannot work. The law says you may use a policy of your own choice instead. The price is capped by law. The most it can cost is R4.50 a month for every R1,000 you owe. On a new Jimny loan that cap is about R1,800 a month at the start. That is a ceiling, not a typical price. If you already have life cover, ask whether it can be ceded to the bank.
Extras at the finance desk. The finance office will offer extras: extended warranties, service plans, tyre and rim cover, scratch and dent cover, shortfall cover and tracking. Add them to the loan and you pay interest on them for six years. Every R10,000 of extras adds about R190 a month. Over 72 months that is about R13,600, and about R3,600 of it is interest. A new Jimny already has a warranty and a service plan, so do not pay for them twice. Ask for a signed quote that lists the price, each extra, every fee, the rate and the total.
Mods on the loan. Roll a roof rack or tyres into the deal and the same maths applies. On the forums, most owners say pay off the car first, then buy the mods.
Scam emails. WesBank has warned about fake emails, sent in its name, offering insurance add-ons and asking for new bank details. Never change your debit order because of an email. Phone the bank on the number on its own website.
Running costs. Fuel, and services once the service plan ends, come on top. Suzuki claims from 6.3 litres per 100 km for the 3-door, a lab figure.
Your rights under the National Credit Act
The National Credit Act sets the rules for car loans in South Africa. These parts matter most.
| The rule | What it means for you |
|---|---|
| Pay extra any time | You can pay extra into your car loan whenever you like, with no penalty. Every extra rand cuts the interest. |
| Settle early | You can pay off the whole loan at any time. On a loan the size of a new Jimny’s, the bank may charge up to three months’ interest. Give three months’ notice and that charge falls away. |
| Fees are capped | The bank’s fees have legal limits. On a Jimny loan expect R1,207.50 once and R69 a month, as on Suzuki’s own offer. |
| Your own credit life | The bank may ask for credit life cover, but you may choose your own policy. |
| Insurance must be fair | The bank can make you insure the car, but not at an unreasonable cost. |
| Affordability check | The bank must check that you can afford the loan. Tell it the truth about your debts. If you hide them, the law stops protecting you. |
Two things people get wrong:
- There is no general cooling-off period on a car loan. The right to cancel within five business days only applies in narrow cases. Do not count on changing your mind after you sign.
- Handing the car back does not end the debt. The bank sells the car. If it sells for less than you owe, you pay the rest.
Use the calculator on every advert
Every Jimny advert on our site has a finance calculator. It adds the bank’s R1,207.50 initiation fee and R69 monthly fee, which Suzuki’s own online calculator leaves out. It shows the instalment, the balloon due at the end and the total you will repay.
The calculator starts at 11.5%. That is a fair middle rate, but change it to the rate your bank actually quotes you. Start with the latest Jimny adverts. If you are trading in, check what your Jimny is worth before you walk into the dealer.
Who should do what
| You | Do this | About a month, at prime |
|---|---|---|
| Want the lowest total cost | Biggest deposit you can, shortest term you can carry, no balloon | 60 months saves about R26,600 over 72 |
| Want a new Jimny for less | Haggle, or buy a discounted new 5-door GL | About R7,000 (10% down) |
| Plan to trade in after six years | A balloon, with a real deposit | About R6,300 (new 3-door GLX, 30% balloon) |
| Budget of R5,000 to R5,500 | A used 2019 to 2022 3-door, no balloon | About R5,000 to R5,500 |
| Want nearly new for less | A 2024 5-door with low km | About R6,400 |
| First car, tight budget | An older 1.3, no balloon | About R2,600 to R3,800 |
| Have the cash | Pay cash, or put most of it down | Cash saves about R150,000 of interest and fees on a new GL, against 10% down over six years |
Buying for a son or daughter? Our first car guide weighs the Jimny against the usual first-car choices.
The bottom line
A new Jimny on finance costs about R7,600 to R8,400 a month at today’s prime, with 10% down and no balloon. The adverts show less because they assume a big balloon. A used current Jimny costs about R5,000 to R6,400, and an older 1.3 about R2,600 to R3,800.
The Jimny has held its value better than most cars, which makes a sensible balloon less risky here. But prices are softening, so do not lean on it. Put money down, pick the shortest term you can carry, and read the quote line by line. Get the insurance quotes before you sign, not after.
For most buyers a Jimny is a want, not a need. Finance it in a way that still works if your income dips. Or, as the old saying goes, die beste kar is die betaalde kar (the best car is a paid-off car).
A big thank you to Suzuki Auto South Africa for the photos from its Jimny shoots, and to Des Sol in Pinetown for the photo of their muddy 3-door. Go and see their work.